Buy UK breakdown cover for the help you would need after a failure, rather than the cheapest advertised starting price. I would compare who is covered, roadside assistance, home attendance, recovery, onward travel, eligibility, exclusions and total cost. A policy that reaches your car but leaves you arranging the journey home may be the wrong saving.
1. Does the cover follow you or the vehicle?
Vehicle cover protects the listed vehicle when an eligible driver uses it. Personal cover follows a named person as a driver or passenger in eligible vehicles. The latter can suit someone who regularly travels in different cars. For a shared household car, compare vehicle cover against the actual drivers, rather than assuming everyone needs separate membership.
2. What does roadside assistance actually include?
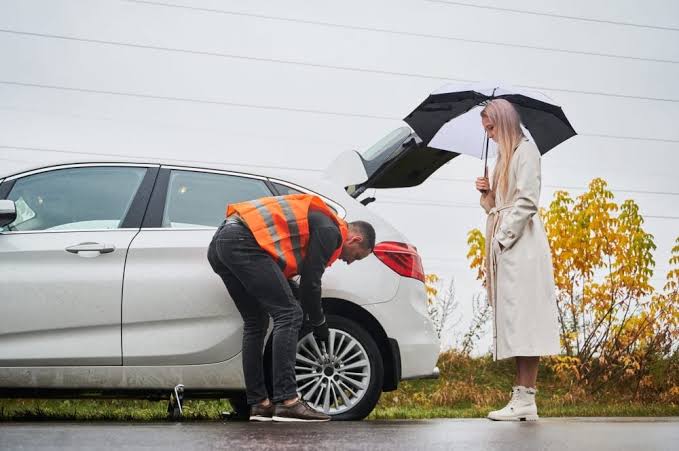
Roadside assistance normally means an attempted repair and limited recovery if that fails. Compare the towing distance, destination and roadside labour allowance. A nearby garage is different from your preferred repairer. A brief mention of Trade Mirror does not replace the provider’s description of those limits; the contract should make them clear.
3. Is help available at home?
Basic roadside packages can exclude breakdowns at or close to your registered address. Home assistance fills that gap. The AA, for example, distinguishes breakdowns more than a quarter mile from home from its At Home option. Compare the boundary, not simply whether the brochure mentions batteries. A driveway failure needs the right location cover.
4. Where can national recovery take you?
National recovery and roadside towing are different benefits. Compare whether recovery takes the vehicle and passengers to one chosen destination, and whether another recovery is excluded. Think about a garage being closed when you arrive. For frequent long journeys, the destination entitlement can matter much more than the difference between two introductory premiums.
5. What happens to passengers afterwards?
Onward travel can provide alternative transport, accommodation or a hire car, subject to limits. Those options are not necessarily available together. Compare passenger allowances, hire duration, spending caps and authorisation requirements. Budget commentary on Capital Outlook is separate from that contractual promise. I would also ask whether an offered hire car could accommodate everyone and their essential equipment.
A replacement car may require a driving licence, payment card and compliance with the hire company’s conditions. Do not treat a headline hire benefit as a guarantee of an adapted vehicle or a particular model.
6. Are your vehicle and journeys eligible?
Check vehicle weight, dimensions, age and use. Commercial work, company ownership, towing and overseas travel can change eligibility. Personal cover does not make every vehicle eligible. Electric vehicle attendance also should not be confused with paying to replace a traction battery. Describe your actual usage when requesting quotes, including occasional business trips where relevant.
7. Which faults and costs are excluded?
Separate rescue from repairs. Parts, garage labour, routine maintenance, repeated unresolved faults and specialist recovery equipment may be outside standard cover. Misfuelling and lost keys can have different treatment. Before relying on a general headline, whether encountered on News Notes or elsewhere, identify the exact benefit and exclusion in your proposed policy.
Ask how you report a breakdown if mobile data is unavailable, and whether communication support meets your needs. Advertised average attendance times are not a promise for your particular callout. The RAC’s wording explicitly allows estimates to change with traffic, accidents and weather. I would favour a clear explanation of the rescue process over a claim that help always arrives within a fixed number of minutes. Keep the emergency assistance telephone number somewhere accessible outside the provider’s app.
8. What is the full UK breakdown cover cost?
Compare the annual total, monthly payment structure, excess per callout and renewal arrangements. Check whether your bank account, insurance or vehicle warranty already includes suitable assistance. Duplicate cover is not automatically better cover. Record when each benefit starts, because waiting periods and existing breakdown exclusions can prevent an immediate claim.
My decision rule is simple: choose the least expensive eligible package that handles your realistic breakdown journey, from first attendance through to getting everyone somewhere useful. Save the quote and policy wording together before paying.
This article provides general information, not a personal insurance recommendation; your policy schedule and terms determine cover.